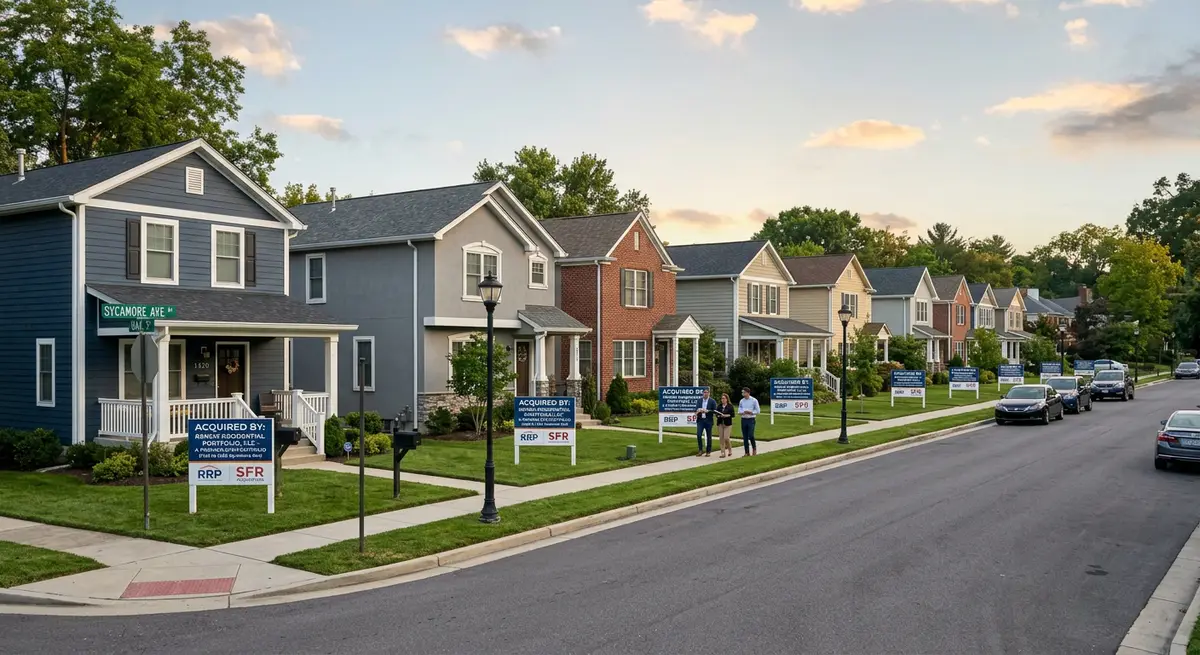
The single-family rental industry is experiencing a wave of consolidation as mid-sized portfolios (50-500 homes) change hands at a record pace, driven by private equity appetite and the operational advantages of scale.
The Consolidation Wave
Through the first three quarters of 2026, there were 47 announced transactions involving SFR portfolios of 50 or more homes, compared to 28 in the same period of 2025. The average transaction size was 180 homes, with total deal volume exceeding $3.2 billion.
Key drivers of the consolidation:
- Cost of capital: Larger operators can access cheaper debt, giving them an acquisition advantage
- Technology investment: Property management software and IoT systems require scale to justify
- Regulatory burden: Increasing compliance costs favor operators who can spread them across more units
- Insurance: Larger portfolios can self-insure or negotiate better rates
Who’s Buying and Who’s Selling
The buyers are primarily three groups: publicly traded SFR platforms, private equity firms with dedicated SFR strategies, and regional operators looking to expand geographically. The sellers are often individual investors or partnerships that built portfolios in the 2010s and are now looking to exit.
Many sellers cite three reasons for exiting now:
- Property values have appreciated significantly since acquisition
- Rising interest rates make refinancing less attractive
- Operational complexity has increased with regulation and tenant expectations
Impact on Local Markets
When a large portfolio changes hands, the impact on local rental markets can be significant. New owners often raise rents to market levels, invest in property improvements, and implement standardized management practices. While this can improve property conditions, it can also reduce affordability for existing tenants.
In markets like Atlanta, Phoenix, and Charlotte — where institutional ownership of SFR is highest — community advocates have raised concerns about the pace of consolidation and its effect on renters.
Opportunities for Independent Operators
Consolidation also creates opportunities for independent, local SFR operators. As large platforms standardize their operations, they often create service gaps that local operators can fill:
- Personalized tenant relationships
- Faster maintenance response
- Flexibility on lease terms
- Knowledge of neighborhood-specific dynamics
Independent operators who focus on service quality and local expertise can compete effectively against national platforms, particularly in markets where tenants value responsiveness and personal attention over branded amenities.
